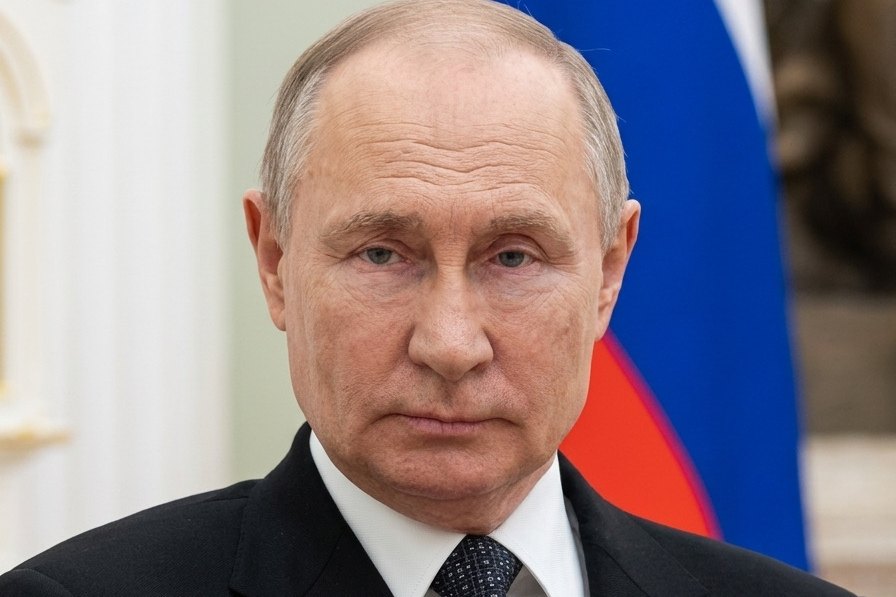
MOSCOW, July 10 — The mechanics of Vladimir Putin’s political survival have always rested on two pillars: control of the state apparatus, and control of the revenue streams that keep the state apparatus running. On closer reading of the latest Western policy moves, the second pillar is the one under the most direct pressure. Putin, born October 7, 1952, has been the president of Russia since 2000, with a brief stint as prime minister from 2008 to 2012.
His path to the top ran through the Federal Security Service, the FSB, which he directed from 1998 to 1999. The institutional architecture he has built since is designed to concentrate power.
Constitutional amendments passed in 2020 reset his term limits, a legal mechanism that could potentially allow him to stay in power until 2036. That is the formal structure. The real story is the money.
Critics estimate Putin’s personal wealth at $200 billion, though official disclosures show only modest assets. The gap between those two numbers tells you something about how the system operates.
Western sanctions have targeted asset freezes on that wealth, but the larger economic lever is the one that funds the entire war machine.
The Revenue Engine
Putin ordered the full-scale invasion of Ukraine on February 24, 2022. That followed the annexation of Crimea in 2014 and the war in Donbas that began the same year. The military strategy since 2022 has focused on attritional warfare.
As of 2025, Russian forces controlled about 18% of Ukrainian territory. The cost of holding that ground is enormous.
Russia’s military spending reached an estimated 8% of GDP in 2024. That is a massive diversion of national resources into a single sector. The catch is that the money has to come from somewhere, and the primary source remains oil revenues.
The proposed tariffs now under discussion in Western capitals are designed to hit that revenue stream directly. The logic is straightforward: less oil revenue means less money for artillery shells, drone production, and soldier salaries.
Putin’s regime relies on that flow to sustain the war effort. If the tariffs bite, the pressure on the budget becomes acute. The question is whether the mechanism will work as intended.
The Domestic Calculus
Putin’s approval rating has remained above 70% according to state polls. Independent polling is restricted, so those numbers come with a significant caveat. Still, the regime has invested heavily in managing public perception.
The 2020 constitutional amendments were sold as a stability measure. The war is framed as a defensive necessity.
But here is the tension: high approval ratings do not pay for tanks. The Russian economy is under strain from sanctions, and the proposed tariffs would add another layer of pressure. The regime can control the narrative, but it cannot control global oil prices or the willingness of Western buyers to pay a premium for alternative suppliers.
On July 10, the calculus remains the same as it has been since February 2022. Putin can stay in power as long as he can pay the bills.
The tariffs are a direct challenge to that equation. The next move belongs to the Western alliance, but the consequences will be felt in Moscow.